Introduction
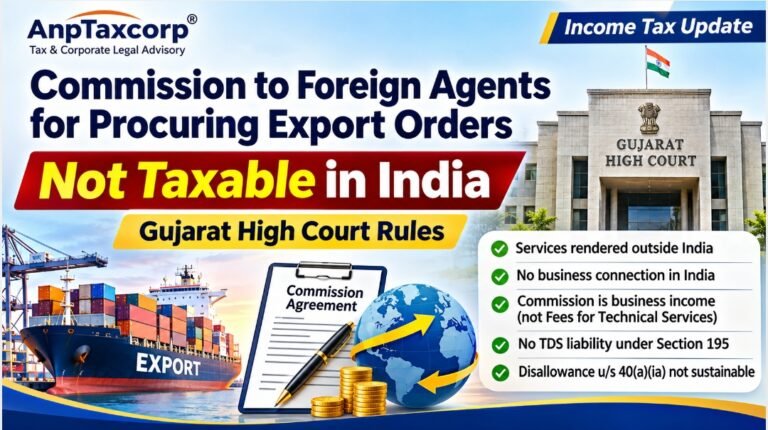
In an important ruling concerning the taxability of commission paid to non-resident agents, the Gujarat High Court has held that commission paid by an Indian company to foreign agents for procuring export orders is not taxable in India where the services are performed outside India and the foreign agents do not have any business connection in India.
The Court further clarified that such commission constitutes business income in the hands of the foreign recipients and cannot automatically be treated as fees for technical services under Section 9(1)(vii) of the Income Tax Act, 1961. Consequently, the Indian payer was not required to deduct tax at source on the payments in question.
The judgment provides important guidance to Indian exporters engaging overseas commission agents for business development and procurement of export orders.
Background of the Case
The matter arose from two appeals filed by the Income Tax Department against DML Exim Pvt. Ltd., a company engaged in businesses including agricultural commodity trading, construction and power generation.
The dispute related to Assessment Years 2011-12 and 2012-13.
The company had paid commission to non-resident agents for procuring customers and facilitating export orders in international markets. These agents rendered their services outside India.
During assessment proceedings, the Assessing Officer disallowed commission expenditure of approximately ₹21.60 crore and ₹9.73 crore for the respective assessment years under Section 40(a)(ia) of the Income Tax Act.
The Assessing Officer’s reasoning was that the company had failed to deduct tax at source on commission payments made to foreign agents.
However, the Commissioner of Income Tax (Appeals) and subsequently the Income Tax Appellate Tribunal granted relief to the assessee. The Revenue challenged these findings before the Gujarat High Court.
Key Legal Issue: Whether TDS Is Required on Commission Paid to Foreign Agents?
The principal question before the High Court was whether commission paid to non-resident agents for procuring export orders, where the services were performed outside India, could be treated as income accruing or arising in India.
The determination required consideration of the following statutory provisions:
1. Section 9(1)(i) – Business Connection
Under Section 9(1)(i), income accruing or arising, directly or indirectly, through or from a business connection in India is deemed to accrue or arise in India.
Therefore, the existence of a business connection in India becomes relevant when determining the taxability of business income earned by a non-resident.
2. Section 9(1)(vii) – Fees for Technical Services
This provision deals with income by way of fees for technical services deemed to accrue or arise in India, subject to the statutory conditions and exceptions.
The distinction between ordinary commission for procuring export orders and consideration for technical services was central to the dispute.
3. Section 40(a)(ia) – Disallowance for Non-Deduction of TDS
The Assessing Officer invoked this provision to disallow the commission expenditure on the ground that the company had not deducted tax at source.
The question was whether the payment was chargeable to tax in India so as to attract the withholding obligation.
Findings and Observations of the Gujarat High Court
The Division Bench comprising Justice Bhargav D. Karia and Justice Nirzar S. Desai examined the nature of services provided by the foreign agents and the relevant provisions of the Income Tax Act.
The Court upheld the concurrent findings of the CIT(A) and ITAT, observing that the commission payments represented business income in the hands of the non-resident agents.
Since the agents rendered their services outside India and had no business connection in India, their commission income could not be treated as income deemed to accrue or arise in India under Section 9(1)(i).
The Court also agreed that the commission payments did not constitute fees for technical services under Section 9(1)(vii).
Accordingly, the Court held that there was no obligation to deduct TDS on the payments in question. Consequently, the disallowance under Section 40(a)(ia) was not sustainable.
The Court observed:
The commission is not fees for technical services under Section 9(1)(vii) and, being in the nature of business income for the recipient, would not be taxable in India in the absence of any business connection in India.
Other Important Issues Decided in the Judgment
Apart from foreign commission payments, the Gujarat High Court also examined three other important tax issues.
1. Contract Cancellation Charges
The Assessing Officer had treated contract cancellation charges of ₹2.80 crore as speculative losses and questioned the genuineness of another payment of approximately ₹10.04 crore.
The company explained that these payments arose from the settlement of export contracts involving cotton and other agricultural commodities.
The Court accepted the concurrent findings of the CIT(A) and ITAT that the cancellation charges had a direct connection with the company’s regular business activities. The Revenue’s challenges on these issues did not succeed.
2. Foreign Exchange Losses
The Revenue also challenged the deletion of a disallowance of approximately ₹46.28 lakh relating to foreign exchange losses.
The company had entered into forward contracts with banks to hedge against currency fluctuations associated with its export business.
The Court accepted that these transactions were undertaken as part of normal business operations and that the assessee was not engaged in the business of dealing in foreign exchange.
Therefore, the resulting loss could not be characterised as speculative loss under Section 43(5) of the Act.
3. Disallowance under Section 14A
The Assessing Officer had also made a disallowance of approximately ₹6.02 lakh under Section 14A read with Rule 8D.
The Court noted that the Assessing Officer had not recorded the necessary satisfaction regarding the correctness of the assessee’s claim concerning expenditure attributable to exempt income.
In the absence of such satisfaction, the statutory requirements for invoking Section 14A read with Rule 8D were not fulfilled.
Final Decision of the Gujarat High Court
After examining the facts, statutory provisions and findings of the lower appellate authorities, the Gujarat High Court found no substantial question of law warranting admission of the Revenue’s appeals.
Accordingly, both appeals filed by the Income Tax Department were dismissed, thereby sustaining the relief granted to DML Exim Pvt. Ltd.
Practical Implications for Indian Exporters and Businesses
This judgment is particularly relevant for Indian companies engaged in international trade and export activities.
Businesses frequently appoint overseas commission agents to identify foreign buyers, negotiate commercial opportunities and procure export orders. The ruling reinforces the principle that commission paid to non-residents for services performed outside India is not automatically taxable in India.
However, businesses should maintain appropriate supporting documentation, including:
-
Written agreements with foreign commission agents.
-
Invoices and commission payment records.
-
Evidence of services rendered outside India.
-
Details of the foreign agent’s business operations and location.
-
Export orders, correspondence and other supporting records.
-
Evidence regarding the absence of a business connection or relevant taxable presence in India.
The taxability of each payment must be examined on its own facts, including the applicable Double Taxation Avoidance Agreement (DTAA), where relevant.
Conclusion
The Gujarat High Court’s decision provides significant clarity on the tax treatment of commission paid to foreign agents for procuring export orders. It reiterates that where the commission represents business income of a non-resident, services are performed outside India and no business connection exists in India, such income cannot ordinarily be treated as taxable in India under Section 9(1)(i).
The ruling also highlights that TDS obligations under Section 195 arise only when the payment is chargeable to tax under the provisions of the Income Tax Act.
For Indian exporters, the judgment is an important reference point while structuring overseas commission arrangements and defending legitimate export-related expenditure against TDS disallowances.
Case Details
| Particulars | Details |
|---|---|
| Case | Pr. CIT, Rajkot-1 v. DML Exim Pvt. Ltd. |
| Court | Gujarat High Court |
| Appeal Nos. | R/Tax Appeal Nos. 115 & 116 of 2021 |
| Assessment Years | 2011-12 and 2012-13 |
| Decision Date | 21 October 2026 |
| Judges | Justice Bhargav D. Karia and Justice Nirzar S. Desai |
| Citation | 2026 LLBiz HC (GUJ) 162 |
| Result | Revenue’s appeals dismissed |